All Categories
Featured
Direct Insurance Advice for Selecting Coverage
Nationwide likewise gives you the ability to basically purchase additional upside possible with their "High-Cap" or "High-Par" Indexed Universal Life insurance coverage investment strategies, which feature an additional 1%-2% fee. Although this reduces an IUL's floor listed below 0%, there may be years when you desire the extra advantage capacity. Varied Set of IUL Crediting StrategiesUnique Multi-Index StrategyHistory of Treating Inforce Policyholders FairlyLarge Size, Mutuality, and Solid Financial StrengthStrong focus on Volatility Control IndexesGood long-term development, but dull early money valuesParticipating policy loan rate is capped to be no higher than 8% Columbus Life Insurance is the IUL arm of the well-rated insurance coverage corporation of Western Southern Group, which entered the IUL arms race in the middle of the last years.
Since their only obligation as a business is to the long-lasting commitment of policyholders, they are more most likely to do right by their inforce block of organization. This can be plainly seen in this screenshot we recently sent out to one of our customers demonstrating how Columbus Life's IUL cap rates have actually gradually increased from 8.75% in December 2022 to 10% precisely one year later as rates ticked up.
The worst IUL companies continually claim to have the very best Indexed Universal Life insurance policy with the greatest cap. However, they'll start with a very high cap to record market share, then rapidly pull the rug out from under their clients once they shelve that item and start a brand-new one.
That way, policyholders obtaining for outdoors financial investment opportunities still had the potential to make at least some favorable arbitrage. Solid S&P 500 cap rateParticipating loan rate is capped at 6% (however has actually been lower for a while)Their recorded history of dealing with in-force policyholders fairlyMutual Holding Business with no outdoors stockholdersTheir uncapped indexed account is presently unappealing and inactionable.
To clarify, all the finest IUL business in this post use some sort of totally free persistent health problem rider, but National Life Group's is arguably the most robust. I likewise want to mention that I am specifically discussing their "Peak Life" product, which is their "bigger case" item providing a more structured charge structure.
Financial Strategies for Veterans
Technically the rider is "totally free", however we've found when stress-testing fees that the death costs are a bit greater than other of the very best IUL companies. This is to be anticipated, and you may have heard me say, "There's seldom any handle insurance coverage. Whatever gets priced completely rather quickly."That said, National Life Group is in the running for the best Indexed Universal Life insurance coverage business for customers looking for a balance of performance, income, and thorough defense.
Don't spend excessive time on these details as your numbers will certainly vary, but this reveals the type of chronic illness rider payments they provide. to discover out which are presently the very best IUL policies with robust Persistent Health problem Riders and solid IUL crediting methods for tax-free earnings if you don't become too ill or injured to function separately.
Indexed Universal Life Insurance has so many moving parts at its core, not to point out all the prospective bells and whistles various companies include to their policies. If you're weighing IUL against your existing retirement accounts, our complete breakdown of covers the crucial distinctions in contribution limitations, tax treatment, and flexibility.
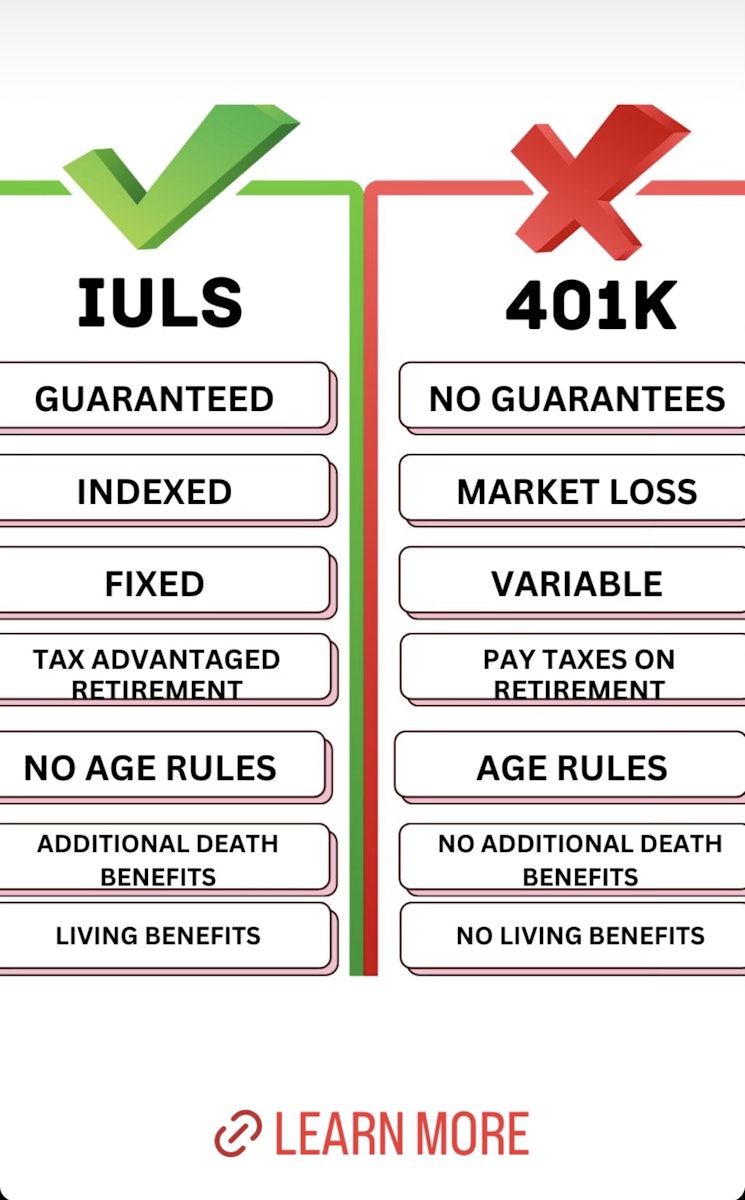
Throughout the majority of the 1900s the only life insurance items were Whole Life and Term. Term insurance coverage offered lower expenses for momentary life insurance protection. Whole Life provided a guaranteed survivor benefit for an ensured level premium, however likewise had actually an attached cost savings component with an ensured irreversible development rate in addition to non-guaranteed dividends.
Benefit Options for US Veterans
The idea with Universal Life is that the development of the cost savings account will minimize the quantity of pure insurance coverage in the policy, which would reduce the rising cost per system of death advantage. In 1986, quickly after the meteoric rise of Universal Life, life insurance coverage companies had the idea of adding a financial investment part.
In 1997, the first Indexed Universal Life product was invented by TransAmerica (not on the list of 2026 Finest IUL business). At first, Indexed Universal Life insurance coverage didn't make a big splash at all.

Latest Posts
Understanding PPO Versus PPO Plans

HMO vs PPO Health Insurance Plans
Best Term Life Options for Veterans