All Categories
Featured
The Mechanics of Whole Life Coverage
1 Investopedia - How Whole Life Insurance Coverage Works. Upgraded May 7, 2025. . Accessed June 18, 2026. 2 Thrivent Whole life insurance: Pros, cons & who it's right for. Upgraded March 10, 2026. . Accessed June 18, 2026. 3 Forbes - What Is Whole Life Insurance Coverage? (& How Does it Work?) Updated December 18, 2024.
Accessed June 18, 2026. 4 Forbes - What Varies Life Insurance? Upgraded November 26, 2024. . Accessed June 18, 2026. Material within this article is offered basic informative purposes and is not provided as tax, legal, health, or monetary guidance for any individual or for any particular scenario.
For complete information, including availability and costs of Aflac insurance, please contact your local Aflac agent/producer. Aflac life plans A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York, Policies NY68200, NY68300 and NY68400.
How Whole Life Insurance Functions
In Delaware, Policy A68100. In New York, Policy NYR68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Not readily available in Delaware, Idaho, New York and Oregon. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100. Not readily available in Delaware, Idaho, New York City and Oregon.
In Delaware, Policy Q60200M. In New York, Policy: NYQ60200M. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M.
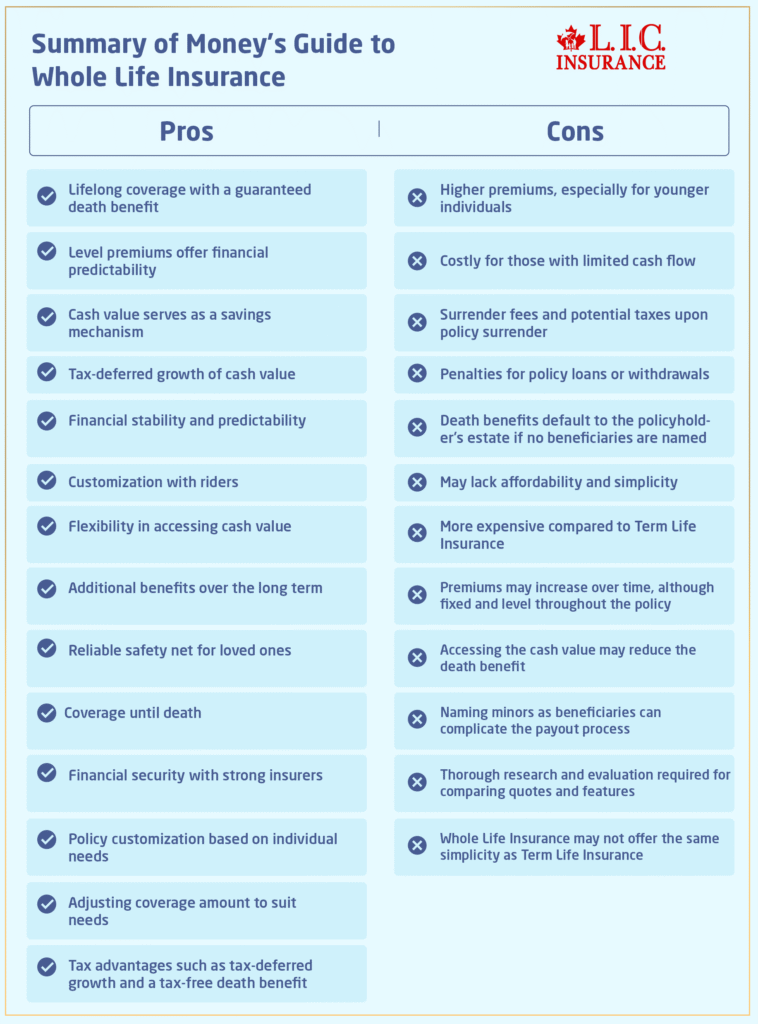
Coverage/plan levels may not be offered in all states, including however not limited to NM or VT. Benefits/premium rates may vary based on strategy picked. Optional riders may be readily available at an additional cost. Policies and riders may likewise contain a waiting duration. Describe the specific policy and rider forms for advantage details, definitions, limitations and exemptions. In this article, we explain what whole life insurance is and compare it to term life insurance coverage, in addition to universal life and variable life insurance. We also discuss how entire life works and why lots of people prefer it over term. Before we leap into this topic, we need to respond to one essential concern: What is whole life insurance? Simply put, it's a type of insurance coverage that ensures coverage for the lifetime of the guaranteed as long as premiums are being paid. Entire life insurance also ensures the premiums and costs will never increase. Whole life insurance coverage is one type of permanent insurance coverage and is very different from term life insurance, which supplies coverage for a specific period just and does not construct cash value. This short article discusses how whole life insurance works Many individuals consider life insurance just in terms of a death advantage. Many of those functions, in some cases called living benefits, are highly preferable, andthis is importantthose functions
Exploring Whole Life Insurance Functions
can not be found in any other type of monetary item in the world. If term life insurance is the most common form of life insurance coverage, entire life insurance coverage is the oldest type of long-term life insurance coverage.(Two exceptions are suicide within the very first 2 years, and lying on the insurance application.)On the other hand,"term policies are mainly developed to last just for a limited time period that will likely end before you die. "Having an insurance coverage that is guaranteed not to end before you do means that a policy you bought to provide defense for your family will protect them, no matter when you pass away. You'll also get a complimentary chapter from Pamela Yellen's New york city Times very popular book on this topic.] Entire life insurance includes an element that term life insurance coverage doesn't have. Part of your premium goes towards a cost savings portion of your policy. This is called the money value of your policy. This enables policies to be designed so that say goodbye to premiums are due as soon as you retire, for instance. You can take out a loan at a rate that is frequently lower than banks use.
Medicare Provider Network CheckThe bigger your cash value, the bigger the loan you can take. You can utilize your cash worth to supplement your other retirement income. Entire life insurance is the only form of life insurance coverage that guarantees of the following: The survivor benefit won't go down The policy won't expire as long as premiums are paid Your premiums won't

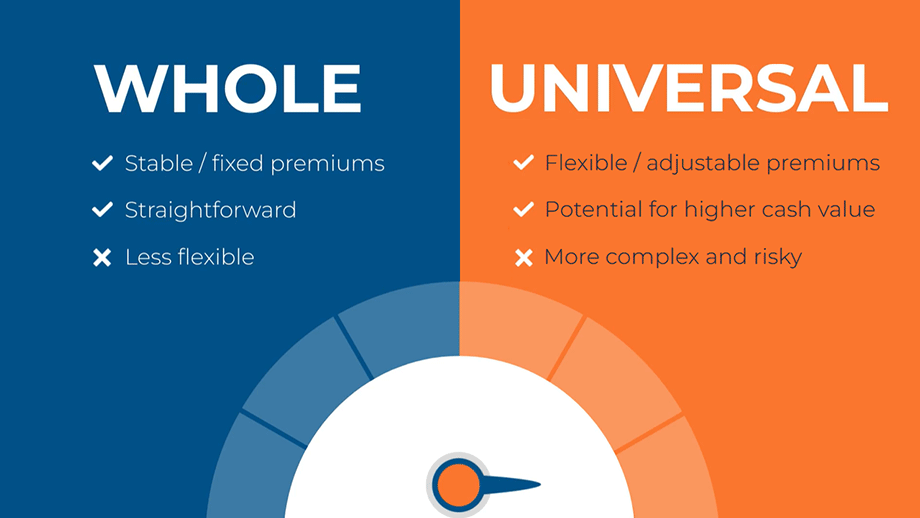
increase Your costs will never increase The insurance provider ensures that the money value of your entire life insurance coverage policy will grow with time. determine just how much your cash value must grow based upon present rate of interest, which, of course, vary in time. enable you to invest funds in policy subaccounts, similar to mutual funds. Your money worth will increase ordecrease, depending upon the efficiency of these subaccounts. What takes place if efficiency of the cash worth of your universal or variable life policy drops? Who needs to ante up more premium to keep your policy in force? You do. Neither choice is great. If you have an entire life policy, you will not have to make those awful choices. The premium, cash worth, and survivor benefit are all ensured. And did you know you can discover out precisely what your surefire premium, money worth and survivor benefit will be at any moment before you choose if it makes good sense to start a whole life policy? Just request a FREE, no-obligation Analysis here to take the primary step. In such a way, it resembles getting an income tax refund. Now, dividends are not guaranteed. It's possible an insurance provider might have a dreadful, terrible, no excellent, extremely bad year . In reality, that's what the company prepares for. And every year that'smuch better than they planned, they can pay a dividend. Get Your FREE Report! Get immediate access to the FREE 18-page Unique Report that exposes how super-charged dividend paying entire life insurance coverage lets you bypass Wall Street, fire your lender, and take control of your financial future. You get to inform the insurance company what to do with your dividend. and this just might be the neatest thing because cupcakesyou can have them use your dividend to purchase more insurance for you insurance you'll never ever need to pay another premium for again. Think of that! You can purchase additional insurance that's paid up, indicating no more premiums will be due on that additionever. If that reminds you of the eighth marvel of the worldcompound interestthat's because the idea is exactly the very same. Just paid up entire life insurance additions construct both your policy's money value and your death benefit. You can discover more here about dividend-paying whole life insurance, which numerous people discover especially exciting. Term life insurance premiums go upsometimes drasticallywith every new term, because much of the cost of insurance coverage is based on how likely you are to die at an offered age, and as you get older, that probability goes up. Universal and variable insurance premiums can increase, tooagain, often drasticallyif cash worth drops dueto low interest rates or poor financial investment performance. So you may be asking, "If it costs more to insure my life with every death year, how can a life insurance coverage company promise my premiums will never increase?" The response is elegantly simpleand it helps describe why entire life insurance coverage is more pricey than term insurance coverage in the early years of the policy.

Latest Posts
Understanding PPO Versus PPO Plans

HMO vs PPO Health Insurance Plans
Best Term Life Options for Veterans